Handing journal entries to an agent: a four-week plan for controllers
Pick one stream, give the agent narrow authority, review a month of drafts and let the evidence decide what it books alone. A practical plan for controllers.

Manoj Tutika7 min read

Working on this yourself? Talk to Mark, our co-founder. We’re here to solve it with you.
On this page
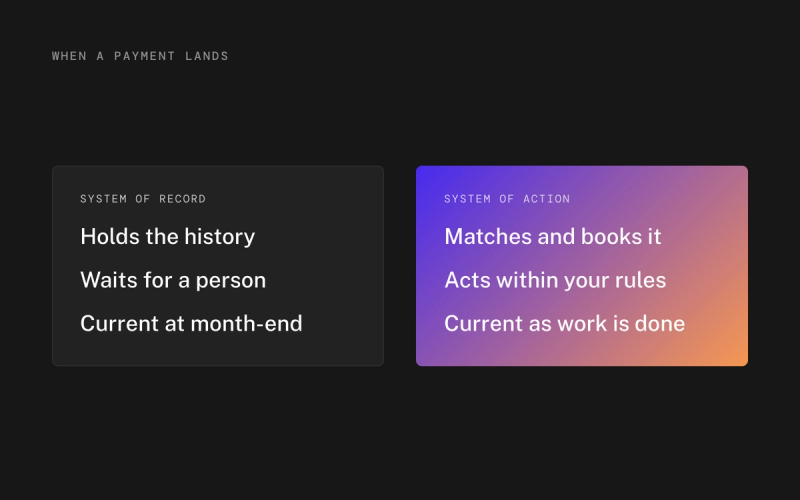
An AI agent books a journal entry by reading the source document, choosing the account, VAT code and period under your rules, testing the draft, and then either posting it or sending it to you with the evidence attached. How much it does without asking is something you grant, per type of entry.
For a controller, the interesting part is not the mechanics. It is the handover. Give an agent too much authority on day one and you will spend the close checking everything twice. Give it too little and it becomes one more inbox. The approach below takes four weeks, starts with a single stream of entries and ends with a decision you can defend to your CFO and your auditor, because it rests on a month of your own data.
Week one: which stream should you hand over first?
Resist the urge to start with the entries that hurt most. Month-end provisions and messy intercompany charges are painful, but they are also the entries where you most want a person thinking. The first stream should be boring.
A good first stream has three properties. It is frequent, so a month gives you enough examples to judge. Every entry comes with a document that states the amounts, so there is something to check against. And something outside the ledger confirms the result later, such as a bank line or a payout report.
Candidates that usually qualify:
- Supplier invoices and the payments that settle them. The invoice carries the net amount, the BTW and the supplier's VAT number. The bank line closes the loop.
- Payment provider payouts. A Stripe or Mollie payout has to be split into gross sales, fees and refunds. The provider's payout report is the source and the bank receipt is the check.
- Card spend. High volume, small amounts, and a receipt behind every line.
- Scheduled period-end entries. Depreciation and prepayment releases follow a schedule you already approved, so the agent is applying a plan rather than forming a view.
Choose one. Then spend the rest of the week writing down how your team books that stream today, including the exceptions everyone knows but nobody has written down. "Software subscriptions go to IT costs, except the design tool, which marketing pays for." "Anything from our Belgian supplier is reverse charged." These sentences become the agent's first rules, and writing them down usually exposes a few inconsistencies in your own team's habits.
Week two: what authority does the agent start with?
Start narrow. In week two the agent drafts every entry in the chosen stream, and nothing posts without a person approving it. At Thred we call this asking first, and every agent can run that way or autonomously; you set it per agent, as our security page describes.
Around that setting, a few controls should apply from the first entry, not be added later:
- Read by default, write by permission. The agent can read bank feeds, invoices and history freely. Writing to the ledger is a permission you grant, and it can be withdrawn.
- Closed periods stay closed. If the invoice belongs to a month you have already reported, the agent proposes it in the open period rather than reopening yours.
- Duplicate and bank detail checks on every draft. Same supplier, same invoice number, same amount: stop. A supplier IBAN that differs from the one on file: stop.
- Amount ceilings. Even after you loosen authority later, entries above a threshold you choose keep coming to a person.
- Corrections leave a trace. A change to a posted entry is a new entry, so the record shows what was booked, what changed and who changed it.
None of this is exotic. It is what you would ask of a new bookkeeper in their first month. The difference is that a system applies the same checks to the four hundredth draft on a Friday afternoon as to the first one on Monday morning.
What should you look for in each draft?
In ask-first mode, your job during week two is review, and it pays to review the same way every time. Take an illustrative supplier invoice: a design studio bills €1,500.00 for campaign work, plus 21% BTW of €315.00, so €1,815.00 in total. A week later €1,815.00 leaves the bank with the studio's name and the invoice number in the description.
The draft for the invoice should read:
- Debit marketing services €1,500.00
- Debit BTW te vorderen €315.00
- Credit accounts payable €1,815.00
And for the payment:
- Debit accounts payable €1,815.00
- Credit bank €1,815.00
Both entries balance. That part is easy to verify and rarely where the problem is. The questions worth asking sit next to the lines:
- Is the reason written down? A short note such as "booked to marketing services, following your rule for campaign design and the three previous invoices from this studio" tells you whether the agent understood your policy or guessed.
- Is the source attached? You should reach the PDF and the bank line in one click, not by searching a mailbox.
- Did the checks run, and what did they find? Open period, VAT amount against the invoice, no earlier booking of this invoice number, IBAN unchanged.
- Would you have booked it the same way? If not, note why. That note is the most valuable output of the whole month.
Week three: what do you do with the drafts you changed?
By week three you will have a pile of approved drafts and a smaller pile of changed ones. The changed ones tell you where the rules are incomplete.
Sort them by cause. Some changes are genuine agent mistakes, such as a cost booked to the wrong department because the invoice was ambiguous. Many are missing rules: the agent did what your written policy said, and the policy was not what your team actually does. A few are judgement calls where two of your own people would disagree.
Turn the first two groups into rules and give the agent the corrected entries as examples. The third group is a signal that this category should stay on approval for now. A good agent applies a correction the next time the same situation arrives, so by the end of the week you should see the change rate falling in the categories you fixed.
Keep counting. For each category within the stream, note how many drafts you approved unchanged and how many you edited. These counts are your evidence in week four.
Week four: which categories can the agent book on its own?
Now decide, category by category, not for the stream as a whole. Recurring suppliers with a clean history and a month of unchanged drafts are good candidates to run autonomously, under an amount ceiling. New suppliers, invoices with an unusual VAT treatment and anything above the ceiling keep coming to you.
This is also the point to look at what the agent did with the cases it was unsure about. A well-behaved agent does not quietly pick the likeliest option. It stops, says what it could not resolve and puts the question to a person: the VAT rate does not match the goods, the supplier is new, the invoice looks like one already booked. If your month of drafts shows it doing that consistently, you can give it more room with confidence. If it guessed, keep it on approval and tighten the rules.
Then pick the next stream and run the same four weeks. Teams that do this stream by stream end up with most routine volume booked continuously, and a review queue that only contains things worth a person's time.
Which entries stay on your desk?
Everything in the four weeks above rests on one assumption: that a document states the amount. Some entries have no such document. The amount is a position the company takes, and someone has to be willing to defend it.
Take a claim from a former supplier for €40,000.00, which your lawyer expects to settle for around half. Whether you book a provision, and for how much, depends on how likely you judge an outflow to be and how reliably you can estimate it. That is a call for the controller, the CFO and possibly the auditor, not for whoever processes the post. The same goes for the bonus accrual that depends on what the board decides in March, or the question of whether this year's development work may be capitalised.
An agent still has a role here. It can make sure these items come up at every month-end instead of being remembered in December, and it can attach the correspondence, last year's treatment and the figures that changed since. The decision, and the signature under it, stays with you. Those entries are few, and they are exactly where your qualifications earn their keep.
Where does Thred fit?
Thred Ledger books transactions as they happen, under your rules, and keeps every entry traceable from journal line to source document. If you would rather keep your current accounting software, Thred Layer runs the same agents on top of it and writes finished entries back. Either way, the four-week handover above is how we suggest teams begin.
To watch an agent draft a real entry and show its reasoning, book a demo.
Frequently asked questions
Which journal entries should you hand to an agent first?
A frequent, low-judgement stream with a document behind every entry and an outside confirmation, such as supplier invoices settled by bank payments or payment provider payouts. Month-end provisions and unusual contracts are a poor place to start.
How long should an agent run in approval mode?
Long enough to see every common case in the stream, which for most teams is a full month. Count unchanged and edited drafts per category, and only let categories with a clean record post on their own.
How do you audit entries booked by an agent?
Each entry should carry its source document, the bank line or report it was matched to, the reasoning, and a record of the agent or person who booked it and who approved it. Corrections are new entries, so nothing disappears from the record.
What happens when the agent is unsure?
It stops and puts the draft in front of a person with the reason, for example a new supplier, a VAT rate that does not fit the goods or a possible duplicate. Your corrections become rules for next time.
Can an agent handle VAT on purchase invoices?
It can read the VAT amount and rate from the invoice, check them against the goods or service and the supplier's country, and book input VAT to the right account. Unusual cases such as reverse charge or mixed-use costs should be confirmed against your rules or with your accountant.
Sources
Read next
- How an accounting agent posts a journal entry, from source document to balanced entry
- Deferred revenue for SaaS annual plans: how to book it and release it monthly
- OSS VAT for EU e-commerce: when it applies, the €10,000 threshold, and how to book it
Where Thred comes in
Thred’s own general ledger, built for agents. Every transaction is booked as it happens, under your rules, and traceable back to its source.