Exceptions are the real work: how finance teams should handle what automation can't
Automation books the routine. The upgrades, refunds, combined payments and foreign-currency deals are where finance time goes. Here is how to handle them well, with SaaS examples.
David van Duijn6 min read

Working on this yourself? Talk to Mark, our co-founder. We’re here to solve it with you.
On this page
An exception in finance is a transaction that cannot be booked with confidence under the rules you already have, because information is missing, two sources disagree, or the right treatment needs a judgement. Automation handles the routine. Exceptions are what is left, and that is where most of a finance team's time goes.
This article is for finance leads and controllers at software and subscription companies, where exceptions cluster around revenue. The examples are SaaS, but the approach works for any business that has automated its routine and found that the remaining work did not shrink as much as expected.
Why are exceptions the real work?
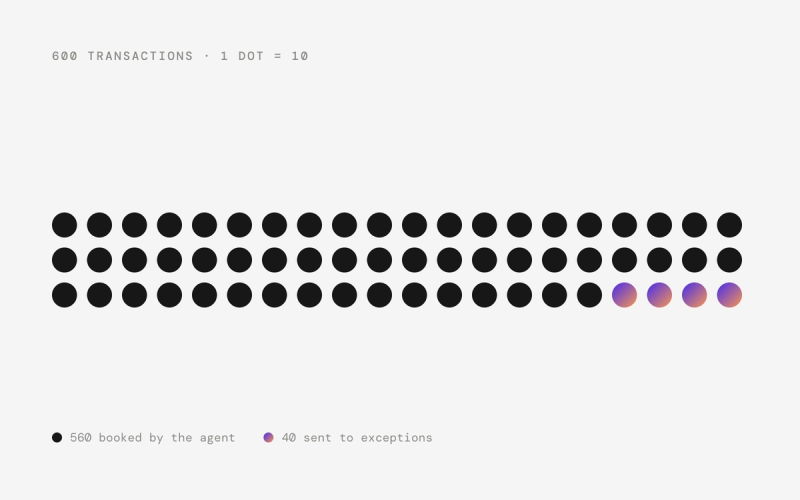
Think of a month with 1,300 transactions. Perhaps 1,280 of them are routine: the same suppliers, the same subscriptions, payouts that split cleanly, customers who pay the right invoice with the right reference. Once those are automated, they take almost no time.
The other twenty take the whole week. Each needs someone to find the contract, read an email thread, ask a colleague, decide on a treatment and book it. They are also where the errors are. A misbooked routine transaction is usually caught by the next reconciliation. A misbooked exception can sit in deferred revenue for a year.
So the quality of a finance function is not measured by how much it automates. It is measured by how well it handles what is left.
What do exceptions look like in a SaaS company?
A mid-term upgrade on an annual plan
A Dutch customer signs an annual plan on 1 January for €12,000 excluding VAT, invoiced up front. You recognise €1,000 of revenue each month and hold the rest as deferred revenue.
On 1 April the customer upgrades to a plan priced at €18,000 a year. Your billing tool issues a prorated invoice for the remaining nine months:
- The price difference is €6,000 a year.
- Nine of the twelve months remain.
- The prorated invoice is €4,500 excluding VAT, or €5,445 including 21% VAT.
The routine rule ("recognise each invoice evenly over its service period") would spread the €4,500 over April to December, which happens to be right. But many billing tools issue the upgrade as a credit for the unused old plan plus a new invoice for the full new plan. The same economic event then arrives as two documents, and a rule that treats each document on its own will recognise the credit and the new invoice on different schedules.
The correct result, whichever documents arrive, is this:
- From January to March you recognise €1,000 a month, €3,000 in total.
- From April to December you recognise €1,500 a month, €13,500 in total.
- Revenue for the year is €16,500, which equals €12,000 plus €4,500.
- Deferred revenue on 1 April, after the upgrade, is €9,000 plus €4,500, which is €13,500.
A refund after cancellation
A different customer on the same €12,000 plan cancels at the end of April and you agree to refund the unused eight months, €8,000 excluding VAT.
If revenue was recognised correctly, deferred revenue at the end of April is exactly €8,000. The refund therefore clears deferred revenue and touches no revenue at all. The €4,000 already recognised for January to April stays. If your books show the refund as negative revenue, something upstream was wrong, and the refund is the moment you find out. A credit note with Dutch VAT also corrects the VAT you charged, so the VAT return for that quarter changes too.
One payment for two invoices
A customer transfers €3,615.00 with the reference "Invoices 0141 and 0152". The open invoices are €2,420.00 and €1,210.00, which add up to €3,630.00. The €15.00 difference is a bank charge the customer's bank deducted.
The money is clearly meant to settle both invoices. Whether you write off the €15.00 as a bank cost, or ask the customer for it, is a policy decision that someone has to make once. After that it is a rule, for example "write off differences under €25 on international transfers to bank charges".
An invoice in pounds
A Dutch SaaS company invoices a UK business customer £10,000 for an annual plan. Because the customer is a business outside the EU, no Dutch VAT is charged on the invoice. Check the treatment for your own services with your accountant.
On the invoice date the rate is €1.1700 per pound, so the invoice is recorded at €11,700 and deferred revenue is €11,700, released at €975 a month. When the customer pays two weeks later the rate is €1.1650, so the bank receives the equivalent of €11,650. The €50 difference is an exchange loss on the receivable, not a reduction in revenue. Revenue stays at €975 a month for the full year, because the deferred revenue was fixed at the rate on the day the invoice was recorded.
Under IFRS 15 and the equivalent rules in Dutch GAAP and the UK's FRS 102, revenue follows the delivery of the service, not the timing of the cash. Each of these four examples is an application of that one principle to a situation the routine rules did not anticipate.
How should a finance team handle exceptions?
Give every exception its full context
An exception that says "unmatched payment €3,615.00" is a research task. An exception that shows the bank line, the two open invoices it probably belongs to, the €15.00 difference and the customer's previous payments is a decision that takes ten seconds. Most of the time spent on exceptions is spent gathering context, so the first job of any system is to gather it before a person looks.
Route it to the person who knows
Finance rarely has the missing fact. Customer success knows whether the upgrade was agreed. The account manager knows whether the refund was promised. The founder knows whether the discount was a one-off. An exception should go to the person who can answer it, in the place they already work, with a specific question rather than "can you have a look?".
Resolve it once, then turn it into a rule
The most expensive exception is the one you handle twice. When a decision is made, record it as a rule the system applies next time, such as how upgrades are treated, the write-off threshold for bank charges, or which revenue account a new product uses. Over a few months the same type of exception should stop appearing.
Set limits for what may be resolved without asking
Some exceptions are small and well understood. Let them be resolved automatically below an amount you choose, with a record of what was done. Keep anything above that amount, anything involving a refund or credit, and anything touching a policy with a person.
Keep the trail
For every exception record what was found, what was decided, by whom, on which evidence and when. Your auditor or accountant will ask about exactly these transactions, because they are the ones that were not routine.
Watch three numbers
- How many exceptions arrive each week. It should fall as rules accumulate.
- How old the oldest open exception is. Exceptions older than a week are usually waiting for someone who has forgotten.
- How many are repeats. A repeat means a decision was made but not turned into a rule.
What changes when an AI agent handles the first pass?
Rules engines have always been able to book the routine. What they could not do is the part in between: read a contract, notice that a credit note and a new invoice describe one upgrade, see that two invoices minus €15.00 explains a payment, or know that the pound rate on the invoice date is the one that counts.
That is the work AI agents are suited to. For each exception, an agent gathers the documents, proposes a treatment with its reasoning, and either books it within the limits you set or asks the right person a specific question. Your finance team stops doing the research and starts doing the deciding, which is the part that needs their judgement.
Where does Thred fit?
Thred is built around the idea that the routine should run continuously and exceptions should arrive ready to decide. In Thred Ledger, transactions are booked as they happen and exceptions are surfaced rather than buried. Everything that needs a person lands in one Inbox, with the document, the bank line and the matched invoices attached. Decisions you make are stored as Memories, the rules and policies specific to your business, which the agents apply the next time.
If you want to keep your current ledger, the same agents run on top of it through Thred Layer, and you decide per agent whether it asks first or acts on its own.
Automation is not finished when the routine is handled. It is finished when the exceptions are handled well. If that is the part of your month that still hurts, book a demo.
Frequently asked questions
How do you account for a mid-term SaaS upgrade?
Recognise the original plan evenly up to the upgrade date, then recognise the remaining deferred revenue plus the prorated upgrade amount evenly over the rest of the term. The total equals everything invoiced for the year, whatever mix of credit notes and invoices the billing tool issued.
Is a SaaS refund booked as negative revenue?
Not if revenue was recognised correctly. A refund of unused months clears the deferred revenue that was still on the balance sheet, so revenue already earned stays. A related credit note does correct the VAT originally charged.
How is foreign-currency SaaS revenue converted to euros?
Advance payments and deferred revenue are generally translated at the rate on the date they are first recorded, and revenue is released at that rate. Differences between the invoice rate and the payment rate are exchange results on the receivable. Check the details with your accountant.
What should be automated and what should stay with a person in exception handling?
Gathering documents, proposing a treatment and resolving small, recurring differences can be automated within limits you set. Refunds, credits, policy choices and anything above your threshold should be decided by a person, with the evidence attached.
How do you measure whether exception handling is improving?
Track how many exceptions arrive each week, how old the oldest open one is, and how many are repeats of a type you have already decided. Falling volume and few repeats mean decisions are being turned into rules.
Sources
Read next
- Real-time books: what changes when your ledger is always current
- Evaluating accounting AI: how to test an agent on your real books
- Choosing an AI assistant for finance work, and what neither ChatGPT nor Claude should do with your books
Where Thred comes in
Thred’s own general ledger, built for agents. Every transaction is booked as it happens, under your rules, and traceable back to its source.