Holding BV and operating BV: intercompany bookkeeping basics
Two BVs, one owner, and every euro between them booked twice. How to handle management fees, current accounts and dividends so both ledgers always agree.
David van Duijn7 min read

Working on this yourself? Talk to Mark, our co-founder. We’re here to solve it with you.
On this page
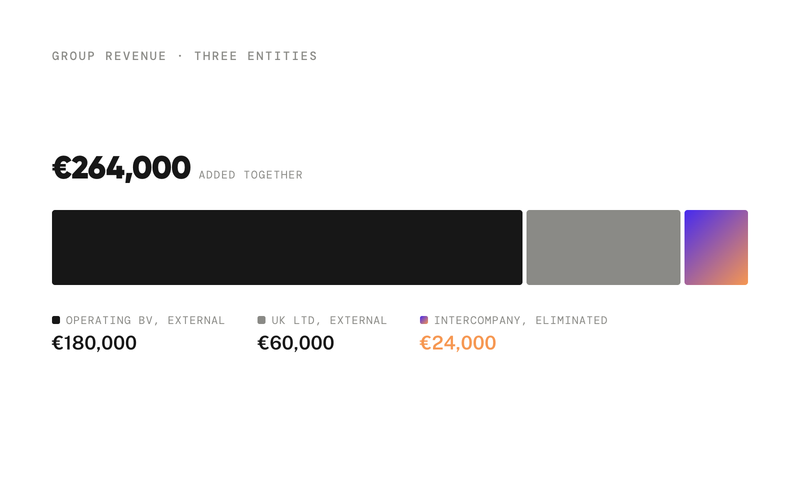
Intercompany bookkeeping for a holding BV and an operating BV means recording every transaction between the two companies in both ledgers, as mirror images. A management fee is income in the holding and a cost in the operating company. A loan is a receivable on one side and a payable on the other. At any month-end, the two sides should agree to the cent.
If you are a founder or owner with a holding above your operating company, a structure that is very common in the Netherlands, you probably set it up for good reasons: separating risk, holding your shares through a company, and making dividends and a future sale simpler. What you may not have counted on is that you now run two administrations, and that most errors live in the space between them.
Why do a holding and an operating BV need separate books?
Because they are separate legal entities. Each BV has its own bank account, its own balance sheet, its own annual accounts and, unless a fiscal unity applies, its own corporate income tax return. The fact that you own and run both does not make them one company.
That has a practical consequence. Every euro that moves between the two must be documented and booked on both sides, with the same amount, the same date and a clear reason. When you or your accountant look at the two ledgers side by side, the intercompany accounts should mirror each other exactly.
The three flows that cover most holding structures are the management fee, the current account and the dividend.
How do you book a management fee between holding and operating BV?
Many owners are employed by their holding and work for the operating company through a management agreement. The holding invoices the operating company a fixed monthly fee for that work.
Take an illustrative fee of €6,000.00 per month. A holding that provides management services for a fee is usually an entrepreneur for VAT, so it charges 21% VAT, which is €1,260.00. The invoice is €7,260.00. Confirm the VAT position for your own structure with your accountant.
In the holding BV:
- Debit receivable from operating BV €7,260.00.
- Credit management fee income €6,000.00.
- Credit VAT payable €1,260.00.
In the operating BV:
- Debit management fees €6,000.00.
- Debit VAT receivable €1,260.00.
- Credit payable to holding BV €7,260.00.
When the operating company pays, both sides clear the intercompany balance against the bank. If it does not pay, the balance stays open and should show the same €7,260.00 in both ledgers.
Two things make this hold up. First, a written management agreement that explains the work and the fee. Second, an actual invoice every month, issued by the holding with all the usual invoice requirements. A fee that only exists as a journal entry is hard to defend.
If you are on the holding's payroll as a director and major shareholder, the rules on a customary salary for owner-directors also apply. That is a payroll and tax question, not a bookkeeping one, so agree the numbers with your accountant.
How does an intercompany current account work?
A current account, in Dutch a rekening-courant, records money that moves between the companies without a sale behind it. The holding lends the operating company cash for a large purchase. The operating company pays a bill on behalf of the holding. You pay a holding expense with the wrong bank card.
Each of these creates a receivable in one BV and a payable in the other. Book them on both sides on the same day, with the same description.
A few rules keep the current account clean.
- Put the terms in writing: the amount, the interest rate, and how and when it will be repaid.
- Charge interest at a rate that independent parties would agree on. Tax authorities look at whether intercompany terms are at arm's length.
- Book the interest every month, not once a year.
- Keep the current account separate from the management fee balance, so you can see which part is a loan and which part is unpaid invoices.
As an illustration, say the holding lends the operating BV €120,000.00 at 5% per year. The annual interest is €6,000.00, so each month the holding books €500.00 interest income (debit current account receivable, credit interest income) and the operating BV books €500.00 interest expense (debit interest expense, credit current account payable). Interest on a loan is usually exempt from VAT, so there is no VAT line here.
How do you book a dividend from the operating BV to the holding?
When the operating company has made a profit, the shareholders' meeting, which in practice is often you, can decide to distribute it to the holding.
Before it does, the board has to check that the company can keep paying its debts after the distribution. Dutch company law requires this test for BVs, and the board can be held liable if a dividend leaves the company unable to pay its creditors. Write the decision and the test down.
Take an illustrative dividend of €80,000.00.
In the operating BV, on the date of the decision:
- Debit retained earnings (other reserves) €80,000.00.
- Credit dividend payable to holding BV €80,000.00.
In the holding BV, on the same date:
- Debit dividend receivable from operating BV €80,000.00.
- Credit dividend income €80,000.00.
When the money is paid, both sides clear the dividend balance against the bank.
On the tax side, two widely used rules usually apply to this structure. A holding that owns at least 5% of the operating company generally falls under the participation exemption, so the dividend is not taxed again in the holding. And while dividend tax is normally 15%, a distribution to a parent company that qualifies for the participation exemption can usually be made without withholding it. The details and filing obligations depend on your situation, so check with your accountant before you pay out.
What about a fiscal unity?
A fiscal unity for corporate income tax lets a parent company and its subsidiaries file as one taxpayer, so profits and losses can be offset against each other and transactions within the group are ignored for that tax. According to the Belastingdienst, it is formed on request, and the parent generally needs to own at least 95% of the shares of the subsidiary.
The Belastingdienst also points out that a fiscal unity for corporate income tax is not the same as one for VAT. Each has its own conditions and consequences.
For your bookkeeping, the important point is that a fiscal unity changes the tax return, not the administration. Each BV still keeps its own books and still needs its own annual accounts. The management fee, the current account and the dividend are still booked on both sides. Whether a fiscal unity suits your structure is a decision to make with your tax adviser.
How do you check that the two ledgers agree?
Run one check every month. List every intercompany account in both ledgers and compare them.
- The holding's receivable from the operating BV equals the operating BV's payable to the holding.
- The current account balances mirror each other, including interest.
- Management fee income in the holding equals management fee costs in the operating BV for the same period.
- Dividend income in the holding equals the dividend booked in the operating BV's equity.
When something does not match, it is almost always one of three things: an invoice booked in one BV but not the other, a payment booked to the wrong intercompany account, or a month where interest was forgotten on one side.
If you find these differences monthly, they take minutes to fix. If you find them at year-end, your accountant has to reconstruct twelve months from two bank statements, and that is what you pay for.
What changes when an agent handles intercompany entries?
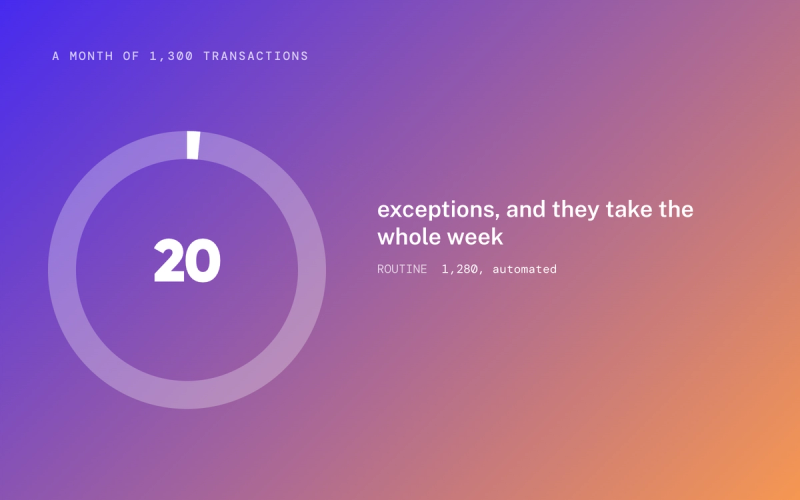
Intercompany bookkeeping fails on consistency, not complexity. An agent is consistent by design.
- When the holding issues its monthly management fee invoice, the agent books it in the holding and books the mirror entry in the operating BV, with the same date and amount.
- Interest on the current account is calculated from the agreed rate and booked on both sides at every month-end.
- A dividend decision is booked in both ledgers on the decision date, and the payment clears both balances when it hits the bank.
- The mirror check runs every month, and any intercompany difference becomes a task with the transaction that caused it.
The owner and the accountant still make the decisions on fees, loans and dividends. The agent makes sure the books follow them in both companies.
How does Thred help with this?
The bookkeeping between two BVs is a pattern: the same fee every month, the same interest every month, the same mirrored entry on both sides. It is exactly what an agent should handle.
In Thred Ledger, each entity has its own ledger and you get one view across all of them, so the holding and the operating company sit side by side. With both ledgers in one place, an agent can prepare the recurring mirrored entries under your rules and flag any difference between the two sides as an exception, instead of a surprise at year-end. If your accounting firm handles your holding structure, they can work in both ledgers from the one workspace they use for all their clients. See Thred for accounting firms.
For an owner, that means you can see the cash in both companies, and what each owes the other, on any day. See how this works for growing businesses.
Want both of your BVs in sync without a year-end reconstruction? Book a demo.
Frequently asked questions
Does a holding BV charge VAT on a management fee?
A holding that provides management services for a fee is usually an entrepreneur for VAT and charges 21% VAT. The operating BV can then generally deduct it. Confirm the position for your structure with your accountant.
Do I need to charge interest on an intercompany current account?
Yes, intercompany loans should carry interest at a rate independent parties would agree on, with the terms in writing. Book the interest monthly on both sides.
Is dividend tax due when an operating BV pays a dividend to its holding?
Dividend tax is normally 15%, but a distribution to a parent that qualifies for the participation exemption can usually be made without withholding it. Check the conditions and any filing obligations with your accountant.
Does a fiscal unity mean I only need one set of books?
No. A fiscal unity for corporate income tax changes the tax return, not the administration. Each BV keeps its own books and annual accounts.
What does a monthly intercompany check involve?
Compare each intercompany account in both ledgers: receivables against payables, current accounts including interest, and fee income against fee costs. Differences found monthly take minutes to fix.
Sources
Read next
Where Thred comes in
Thred’s own general ledger, built for agents. Every transaction is booked as it happens, under your rules, and traceable back to its source.