A finance automation playbook for growing SMEs: what to automate first, second and never
Not every finance task should be automated at the same time. Start with high-volume work you can check, then move to recurring judgement, and keep real decisions with people.

Manoj Tutika7 min read

Working on this yourself? Talk to Mark, our co-founder. We’re here to solve it with you.
On this page
A finance automation playbook is an order of work. Automate the high-volume tasks whose results you can check first, the recurring tasks that need some judgement second, and keep the decisions that change your business with people, supported by software that prepares them.
Most growing companies get the order wrong. They buy a reporting tool before the books are current, or they automate a payment run before anyone trusts the invoice coding behind it. The result is faster wrong numbers. This playbook is written for founders who want finance off their plate and for finance leads who need more capacity from the team they already have.
How do you decide what to automate first?
Ask four questions about every recurring task in your finance week.
- How often does it happen? A task that happens 400 times a month is worth more automation effort than one that happens twice a year.
- Can you check the result? A bank line matched to an invoice either agrees or it does not. A judgement on whether a customer will pay is much harder to verify.
- What does a mistake cost? A wrong cost category is fixed with one correcting entry. A payment to the wrong supplier is cash out of the door.
- Does it depend on context only a person has? A discount agreed on the phone, a dispute with a supplier, a plan to restructure a team.
A task that is frequent, easy to check, cheap to correct and light on hidden context goes first. A task that is rare, hard to check, expensive to get wrong and full of context stays with you.
What should you automate first?
The first wave is the work that keeps the books current. Everything else in finance depends on it, so it pays back fastest.
Bank and payment reconciliation
Every bank line, card transaction and payment provider payout needs to be matched to an invoice, a bill or a known recurring cost, and booked. It is the highest-volume task in almost every SME, the rules are stable, and the result is verifiable because the bank balance has to agree with the ledger. If you sell through Stripe, Mollie or Shopify, include the payouts here. They are net amounts and need to be split into sales, fees and refunds before they mean anything.
This is where an AI agent differs from the bank rules you may already have in Exact Online. A rule matches on fixed text. An agent reads the bank line, the open invoices, the payout report and the supplier's history together, proposes the match, and asks you only when the evidence does not line up.
Supplier invoice capture and coding
Invoices arrive by email, in portals and on paper. Reading them, checking the supplier, the VAT rate and the amount, and coding them to the right cost account is repetitive work with a clear right answer for most invoices. Once a supplier has been booked the same way a few times, the next invoice should not need a person at all. An agent learns that pattern from your own booking history instead of from a template someone has to maintain.
Collecting missing documents
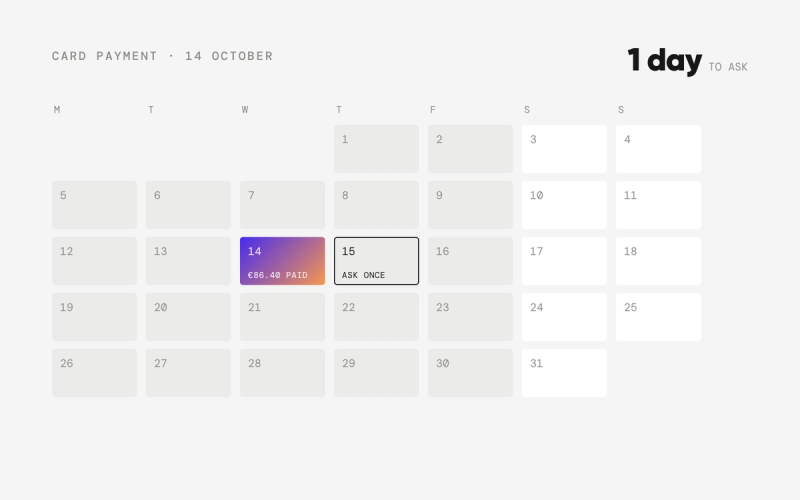
A bank payment without a receipt is a gap in your books and, in the Netherlands, a gap in the administration the Belastingdienst expects you to keep. Asking for receipts is low-value work that people put off. Software does not put it off. It asks the cardholder the day the transaction appears, and asks again a few days later.
These three tasks together decide whether your books are current on a Tuesday afternoon or only after month-end. Get them right before anything else.
What should you automate second?
The second wave is recurring work that needs rules plus some judgement. It is still repetitive, but a mistake is more visible, so you want a period of review before you let it run on its own.
- Invoice approvals. Route each supplier invoice to the right budget owner, with the purchase order or contract attached, and chase the approval. The routing is a rule. The approval stays a human decision, but the preparation does not need to be.
- Payment runs. Prepare the batch of approved invoices due this week, check for duplicates and changed bank details, and present it for one sign-off.
- Collections. Send reminders on time, in the right tone for each customer, and answer the simple questions ("can you resend the invoice?") without involving you.
- Month-end entries. Accruals, prepayments, depreciation and deferred revenue follow schedules. Once the schedule is set, preparing the entries every month is mechanical. Approving them is not.
- VAT preparation. In the Netherlands most companies file quarterly, in the UK the return goes through Making Tax Digital software. Either way, a VAT return prepared from current books is a review task rather than a reconstruction project. Check the result with your accountant before you file.
The pattern for this wave is the same: let the software prepare and propose, review its work for a few cycles, then widen what it may do alone. In Thred Layer, every agent runs in one of two modes, "Ask me first" or "Autonomous", and you choose per agent. Most teams start reconciliation on autonomous within weeks and keep payments on ask-first for much longer. That is the right instinct.
What should you never automate?
"Never" is strong, so let us be precise. You should never hand these decisions to software. You should absolutely let software prepare them.
- Writing off receivables or forgiving debt. It is a commercial decision about a customer relationship, not a bookkeeping task.
- Choosing accounting policies. How you recognise revenue on a new product, when you capitalise development costs, what your materiality threshold is. These are set once by people, with your accountant, and then applied by software.
- Tax positions. Whether a cross-border sale falls under reverse charge or the OSS scheme, or how a restructuring is treated, needs an adviser who knows the facts. Software can flag the question. It should not answer it alone.
- Paying a supplier whose bank details just changed. Changed bank details are the classic fraud pattern. A person confirms by phone, every time.
- Signing off the annual accounts. A registered accountant signs, and you as director are responsible for what is in them.
- Difficult conversations. A customer disputing a large invoice, a supplier you are about to drop. Draft the email with help if you like, but send it yourself.
A useful test: if the honest answer to "who decided this?" should be a person's name, keep a person in the loop.
What does this look like in a founder's week?
Take a founder of a 25-person company on Exact Online, without an in-house controller. Before automation, finance takes most of Monday morning plus scattered evenings: forwarding receipts, approving invoices in three places, answering the accountant's questions about bank lines from six weeks ago.
After the first wave, the bank lines are matched daily, invoices are coded on arrival and receipts are requested by the software. The accountant's question list shrinks because the questions were asked at the time, when people still remembered the answer. After the second wave, Monday is a fifteen-minute review: approve the payment batch, glance at the collections list, answer the two items that genuinely need the founder.
Thred's agents do this work on top of the ledger you already use, and push the finished entries back to it, so your accountant keeps working where they always have. For the company in the example, see how it works for businesses.
Where do automation projects go wrong?
Automating a broken process. If nobody agrees who approves marketing spend, software will route invoices to the wrong person faster. Fix the rule first, then automate it.
Starting with reports. A dashboard on books that are six weeks behind is a dashboard of last quarter. Reporting belongs after the books are current, not before.
Buying a tool per task. A receipts app, an approvals app, a collections app and a reporting app means four places where data can disagree. Look for one layer that works on all of it, against the ledger you keep.
Never widening autonomy. Some teams keep every agent on review forever and then conclude automation saved nothing. Measure how often you change what the software proposed. When that number is close to zero for a task, let it run.
Losing the audit trail. Every automated entry should show the source document, the rule that was applied and who approved it. If you cannot answer "why was this booked like this?" six months later, the automation has made your books harder to defend, not easier. More on how Thred handles access and approvals is on our security page.
A simple order of work
- Connect your bank accounts, payment providers and the inbox where invoices arrive.
- Automate bank and payout reconciliation, invoice coding and receipt collection. Review daily for two weeks.
- Move reconciliation and coding to autonomous where your correction rate is near zero.
- Add approvals, payment preparation, collections and month-end schedules on ask-first.
- Prepare the VAT return from the current books and review it with your accountant.
- Only then, build the reports and dashboards you want to steer on.
The order matters more than the tools. Current books first, recurring judgement second, real decisions always with people.
If you want to see this order of work running on your own ledger, book a demo.
Frequently asked questions
Which finance process gives the fastest return on automation?
Bank and payment reconciliation, in almost every SME. It is the highest-volume task, the rules are stable, and the bank balance tells you immediately whether the result is right. Every report and filing downstream depends on it.
Should a small company automate its VAT return?
Automate the preparation, not the sign-off. A VAT return prepared from books that are reconciled daily is mostly a review task. Someone who understands your transactions, ideally with your accountant, should still check it before it is filed.
How long should automated bookkeeping run under review before it goes autonomous?
Long enough to see how often you change what it proposes. For reconciliation and invoice coding that is often a few weeks. Payments and anything involving refunds or credits usually stay on review for much longer.
Is it safe to let software pay supplier invoices?
Let software prepare the payment batch, check for duplicates and flag changed bank details. A person should approve the batch, and any change of a supplier's bank account should be confirmed by phone before money moves.
Do I need to replace Exact Online to automate finance?
No. Agents can work on top of the ledger you already use, read your bank, inbox and payment data, and push finished entries back. Your accountant keeps working in the same administration.
Sources
Read next
- AI agents for finance teams: the recurring work they take over
- Bank reconciliation: how to do it step by step, and how to automate it
- Coding agents for finance teams: what you can build and the guardrails
Where Thred comes in
Finance agents running on top of your existing ledger. You set the rules, approve the work and handle the exceptions. No migration.