Year-end close in the Netherlands: a practical checklist for small companies
The jaarafsluiting is easier than it looks if you split it into what must be true about your books and what has to be filed when. A checklist for Dutch BVs.
David van Duijn7 min read

Working on this yourself? Talk to Mark, our co-founder. We’re here to solve it with you.
On this page
A year-end close (jaarafsluiting) is the work of making your books complete and correct for the full financial year, so the annual accounts and the corporate income tax return can be prepared from them. For a small Dutch company, it comes down to reconciling every balance, booking what belongs to the year, and meeting two filing deadlines.
If you own or run a Dutch BV, January is when your accountant starts asking for things. Bank statements, a stock count, that one invoice from March. The questions arrive in batches, and each batch reveals something that should have been booked months ago.
It does not have to work like that. Most of a year-end close is the same work as a month-end close, done one more time with a bit more care. If the months were closed properly, the year mostly follows.
Below is the checklist we use when we think about a small company's year-end. It is written for owners and finance leads of companies with a handful to a couple of hundred people. Your accountant will have their own list. This one helps you arrive with fewer surprises.
What has to be true about your books on 31 December?
Every bank and payment account reconciles
The balance in the ledger for each bank account, card account and payment platform (Stripe, Mollie, PayPal and the like) should equal the statement on 31 December, to the cent. Payment platforms are where differences hide: fees, refunds and payouts that straddle the year end.
Receivables and payables are real
Go through open sales invoices. Anything that will not be paid needs a decision: chase it, credit it, or provide for it. Do the same for open purchase invoices. A supplier invoice that shows as unpaid but was paid from a personal card is a classic year-end find.
Costs and revenue sit in the right year
This is where accruals and prepayments come in. Two simple illustrative examples:
- An energy bill for December arrives on 20 January for €1,210 including 21% VAT. The €1,000 cost belongs to the old year, so you book it as an accrued expense on 31 December.
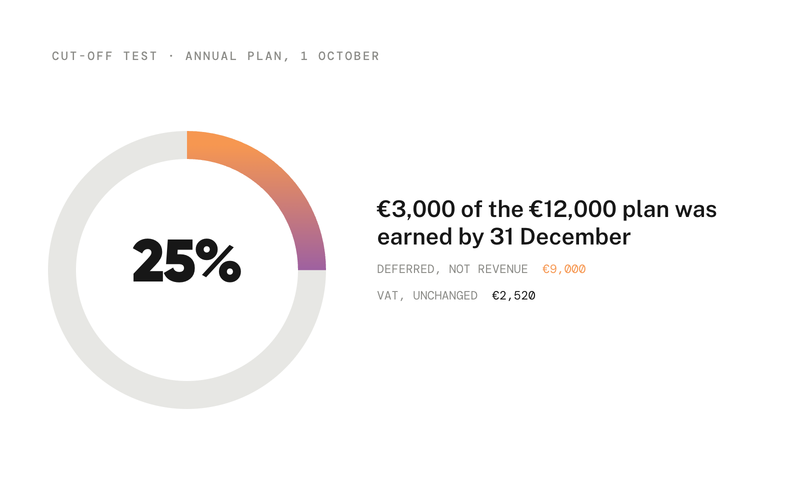
- In October you paid €2,400 for an annual software licence running October to September. Three months, €600, belong to this year. The remaining €1,800 is a prepayment on the balance sheet.
The same logic applies to revenue: work delivered in December but invoiced in January belongs to December.
Fixed assets and depreciation are complete
Check that every asset bought this year is on the fixed asset register, that disposals are removed, and that depreciation has been booked for all twelve months.
Stock is counted and valued
If you hold inventory, count it at or close to year end and compare the count with the ledger. Write down anything damaged, obsolete or unsellable.
VAT accounts tie to your returns
The balance on your VAT accounts should match what you filed for the fourth quarter (or December). Compare the year's sales and purchases with the total of the four returns. If you find an error, the Belastingdienst lets you correct up to €1,000 in your next return; larger errors need a separate correction (suppletie).
Payroll reconciles to the payroll tax returns
The wages in your ledger should equal what your payroll provider reported to the Belastingdienst for the year. Check the holiday allowance reserve too: in the Netherlands employees build up holiday allowance (vakantiegeld) of at least 8% of their gross salary, often paid out in May, and the amount built up but not yet paid belongs on the balance sheet.
The director's current account is clean
In many small BVs the owner pays some company costs privately, or the company pays some private costs. These go through a current account with the director-shareholder (rekening-courant). Make sure every item on it is documented and that the balance is one you are comfortable explaining.
Corporate income tax is estimated
Your accountant will compute the final number, but booking an estimate of corporate income tax (vennootschapsbelasting) for the year gives you a realistic result and balance sheet to discuss.
What do you have to file, and when?
Two deadlines matter most for a typical BV with a calendar financial year.
Corporate income tax return
The corporate income tax return is due five months after the end of the financial year, so by 1 June for a calendar year. You can ask the Belastingdienst for an extension; through Mijn Belastingdienst Zakelijk you can request one until 1 November. Many companies file through their accountant, and tax advisers can use a separate extension arrangement with the Belastingdienst for their clients. Ask yours which applies to you.
Annual accounts at KvK
Every BV files its annual accounts (jaarrekening) with the Chamber of Commerce (KvK). The accounts must be filed within eight days after they are adopted, and in any case no later than twelve months after the end of the financial year. For a calendar year, that is the end of December of the following year.
How much you file depends on your size class. KvK classifies companies by assets, turnover and employees. A micro company has assets under €450,000, turnover under €900,000 and fewer than 10 employees, and you fall into a class if you meet at least two of the three criteria for two consecutive years. Micro and small companies file a much shorter version than larger ones. Check the current thresholds on the KvK site, since they are revised from time to time.
Keeping the records
Your basic records, including the general ledger, the sales and purchase records and the receivables and payables, must be kept for seven years. Records about real estate have a ten-year period.
How do you keep the year-end from becoming a project?
The honest answer is that a year-end close is only hard when the months before it were not closed. Every item on the checklist above is easier on a single month than on twelve.
So the real checklist is monthly:
- Reconcile bank and payment accounts every month, ideally every day
- Chase missing documents while they are still recent
- Book accruals and prepayments monthly, not once a year
- Run depreciation every month
- Tie the VAT accounts to each return as you file it
When that is in place, the year-end becomes a review rather than a reconstruction. Your accountant spends their time on the questions that need judgement, such as valuation, provisions and tax positions, instead of on chasing receipts.
How do agents change the year-end close?
The checklist does not change. What changes is when, and by whom, each item gets done. Here is what that looks like when agents work through the year instead of an accountant working through January.
- Reconciliation runs on every bank sync. Each bank and payment platform line is matched to an invoice, a payout or a fee the day it arrives. On 31 December there is nothing left to match, only a short list of exceptions.
- Missing documents are chased in the month they go missing. An agent notices that a bank payment has no invoice behind it and asks the supplier or the person who paid, by email, while the payment is still fresh.
- Accruals are proposed, not remembered. A supplier that billed every month except December is spotted, and the agent drafts the accrual for the missing month with the amount based on the previous invoices. You approve it or change it.
- Prepayments and depreciation are scheduled. The €2,400 licence from the example is spread over twelve months automatically, and each new asset gets its depreciation schedule when it is booked.
- VAT and payroll tie-outs happen per period. The VAT accounts are compared with each return as it is filed, and payroll costs with each payroll tax return, so the year-end comparison is a formality.
- Receivables are reviewed continuously. Invoices older than ninety days are flagged with their collection history, so the bad debt discussion starts with facts.
What stays with people are the judgement calls: stock valuation, provisions, bad debts and how to treat an unusual transaction. Those belong with you and your accountant, and agents should bring them to you with the evidence attached rather than decide them.
At Thred, our agents do this work on top of the accounting software you already use, or in Thred's own ledger. Accruals, depreciation and reconciliations are prepared for your approval and booked, and anything unclear goes to an inbox for a person. Annual accounts and corporate income tax returns are prepared from the live ledger and signed off by a registered accountant, either yours or one of ours. You can see how that fits a growing company on our page for businesses, or read how it runs on top of your existing setup on Thred Layer page.
The checklist above is general. For anything specific to your company, such as valuation of stock or a fiscal unity, check with your accountant.
If you would rather spend January on next year than on last year, book a demo and see what a continuously closed ledger looks like.
Frequently asked questions
When must a Dutch BV file its annual accounts with KvK?
Within eight days after the accounts are adopted, and in any case no later than twelve months after the end of the financial year. For a calendar financial year that means by the end of December of the following year.
When is the Dutch corporate income tax return due?
Five months after the end of the financial year, so 1 June for a calendar year. An extension can be requested, online until 1 November, and tax advisers can use a separate extension arrangement for their clients.
What is a micro company in the Netherlands?
KvK classifies a company as micro when it meets at least two of three criteria for two consecutive years: assets under 450,000 euros, net turnover under 900,000 euros and fewer than 10 employees. Micro companies file a much shorter set of accounts.
How long do I need to keep my bookkeeping records?
Seven years for the basic records, such as the general ledger, sales and purchase records and receivables and payables. Records relating to real estate must be kept for ten years.
What is the difference between an accrual and a prepayment?
An accrual records a cost that belongs to this year but is invoiced next year. A prepayment records the part of a payment made this year that covers next year, so it sits on the balance sheet until that period arrives.
Sources
Read next
- Month-end close in Exact Online: a step-by-step guide
- Accruals: how to book them, with examples, and how to automate them
- Accrued expenses (accruals)
Where Thred comes in
For finance leaders who want more capacity without more headcount.